Insurance Agency Business Plan Template

This insurance agency business plan template is for people starting a multi-line insurance brokerage. That means selling several types of coverage under one roof, like auto, home, life, health, and business insurance.

Insurance agencies work in a unique way, though. Lenders don't just look at your sales. Instead, they look at your "book of business." This term refers to all the policies you manage.

Three things matter most to them. They want to see your commission on each type of policy. They want to know how many customers renew each year. And they want to see whether your servicing costs grow slower than your sales.

Your plan needs to show all of this, using both words and numbers together. Here's what that looks like in real numbers. This template comes with a sample company, HarborShield Insurance. It sells four types of insurance with auto and home leading the way. By Year 3, its profit margin reached a healthy 56%. Getting there takes $99,000 in funding, used not to buy someone else's customer list, but to build strong internal systems and keep cash on hand for everyday needs.

What You Get with PrometAI’s Insurance Agency Business Plan Template

Executive summary

Executive summary

Market analysis

Market analysis

Revenue model

Revenue model

Cost Structure

Cost Structure

Financial projections

Financial projections

Funding strategy

Funding strategy

Risk analysis

Risk analysis

Production planning

Production planning

What Makes a Strong Business Plan
for an Insurance Agency

Let's clear up a common mix-up first. When people write an insurance agency business plan, they often talk about "premium volume." That's the total price of all the insurance policies sold.

But here's the thing: an insurance agency doesn't keep that money. The agency only earns a small cut of it, called a commission. That's the real income, and it's a lot smaller than the premium total. So what should a good business plan for an insurance agency actually focus on? Three simple things.

First, the commission rate. This is the percentage the agency earns on each policy it sells. Second, the number of policies the agency manages. Third, the retention rate. This tells you how many customers renew their policy year after year, instead of leaving. Together, these three numbers tell you how healthy the agency really is.

Now, what makes one agency more valuable than another? It's not the deals they have with insurance companies, called carriers. Any agency can set those up. It's not the products either. A home insurance agency across town can sell the exact same policy, from the exact same carrier, at the exact same price. What actually matters is something called the renewal book. That's the group of loyal customers who keep renewing their policies every year. Keeping those customers is what makes an agency worth something over time. That's why a good plan talks about keeping customers before it talks about finding new ones.

While explaining all this, it also helps to be honest about the risks. A carrier could end its partnership with the agency. Prices could suddenly go up. And every time the agency adds a new type of insurance or starts working in a new state, there are more rules to follow. Being upfront about these risks is part of what makes a plan trustworthy. You can read more about spotting these real risks here.

Timing matters too, and it's easy to miss. Before an agency can sell even one policy, it needs a license, formal approval from insurance carriers, and a computer system to manage everything. All of this costs money upfront, before any income starts coming in. You can learn how to estimate these startup costs here.

Once the agency is running, different types of insurance bring in money differently. Auto insurance usually starts paying small amounts fairly quickly. Insurance for businesses, called commercial insurance, pays more, but takes longer to close. Life insurance takes the longest of all to build up, but it often becomes the most valuable type over time.

Understanding this timeline helps avoid a common mistake: assuming the agency will grab a huge share of the market right away. In reality, most insurance markets already have a lot of agencies competing, so a brand-new one usually starts with just a small piece of the pie. You can learn more about estimating this market share here.

Finally, think ahead to renewal season, the time each year when customers decide whether to keep their policy or switch. This is where a business really gets tested. What happens if a carrier raises its prices by 12%? What if it ends its partnership with the agency? What if a competitor offers a cheaper auto policy, and auto insurance happens to be the line paying most of the bills?

A strong plan has answers ready for all of this. Work with more than one carrier, so the agency isn't dependent on just one. Build a system that can handle more customers as the agency grows. Keep enough money saved to get through slow periods. And add new types of insurance one at a time, instead of all at once.

What Makes a Strong Business Plan

Financial Planning Considerations
for an Insurance Agency Business

Two agencies can sell the same amount of insurance and still be worth very different amounts. Why? It comes down to how many customers renew each year, and which types of insurance they buy. A strong business plan for an insurance agency shows both clearly, along with the systems needed to grow.

Commission structure by line

Commission structure by line

A commission is the small cut an agency earns from each policy it sells. New policies pay differently than renewals, and every insurance type pays differently too. Show each type on its own. Blending them together hides where the money really comes from.

Retention and persistency

Retention and persistency

Retention just means keeping the customers you already have. It's what makes an agency valuable over time. Even a small shift, just five percent, can affect revenue more than any guess about new sales.

Servicing cost per policy

Servicing cost per policy

Every policy needs ongoing support, like handling claims or renewals. This takes staff time, whether the policy is new or old. Show how this cost grows as the agency adds more policies.

Licensing, appointments, and compliance

Licensing, appointments, and compliance

Agents need a license to sell insurance, and approval, called an appointment, to sell a specific company's policies. These renew yearly, they're not one-time costs. List each one with its renewal date.

Working capital and commission lag

Working capital and commission lag

Money doesn't arrive right away. The agency has to wait for the insurance carrier to process everything first. A good business plan template for an insurance agency accounts for this gap, keeping enough cash on hand to cover payroll during the wait.

Common Mistakes in
Insurance Agency Business Plans

01

Mixing up premium and revenue

Saying "$2 million in premium written" sounds great, but it's not actually true to the agency's income. Premium is just the total cost of the policies sold. The agency only keeps a small cut of that, the commission. If a plan doesn't spell that out, it comes off as misleading.

02

Claiming retention without proving it

"90% retention" shows up in nearly every plan, rarely explained. It should tie back to what you sell, how you treat customers, and current rates. Otherwise, it's just a guess.

03

Growing policies faster than staff

Triple the policies, keep the same staff, and service starts to slip. More policies mean more claims, renewals, and questions to handle.

04

Leaning on too few carriers

If most of your business runs through just one or two insurance carriers, that's a problem waiting to happen. Lose that relationship, or have them raise their rates, and it hits your whole business at once. It's smarter to work with a few different carriers.

05

Forgetting the wait for commission

Commissions don't show up right away. So it's totally possible to look profitable on paper and still not have enough cash to pay your team. A good plan sets aside money ahead of time to cover that gap.

06

Skipping what investors look for

No growth plan, no risk ownership, no spending plan, no backup thinking. These gaps stand out to investors fast, and matter as much as the numbers.

Why Founders Use PrometAI to Build
Their Insurance Agency Business Plan

Most people don't realize this, but an insurance agency is really three businesses at once. One brings in new customers. One takes care of the policies already sold. One helps people renew each year. Each of these makes money in its own way. Mix them all together, and you lose track of where your profit is really coming from.

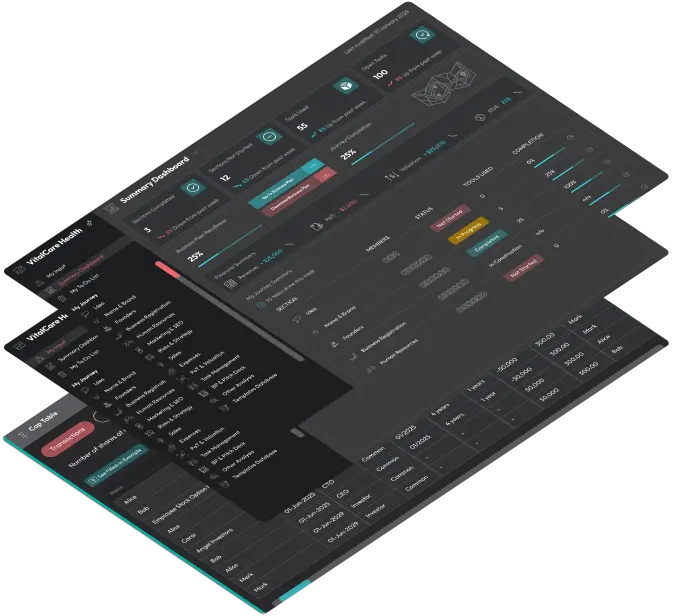
That's the problem PrometAI's AI business plan generator is built to fix. It keeps your story, your guesses about the future, and your numbers all linked together. Change one thing, like how many customers stay, and everything else updates on its own. Nothing gets lost or forgotten.

Running an insurance agency also means dealing with paperwork most businesses don't have. You need a license to sell insurance. You need approval from each insurance company you work with. You have deadlines to meet. You need coverage in case you make a mistake. And someone has to be in charge of each of these. People reading your plan will look for all of this, and they'll notice if it's missing. PrometAI's financial model keeps this right next to your numbers, so everything comes from the same place and fits together.

Here's the really useful part, though: testing "what if" questions. What if an insurance company raises its prices? What if fewer customers stay this year? What if you wait a few extra months to add a new type of insurance? PrometAI updates your whole financial picture right away, so you always know where things stand. That means when someone asks a hard question while comparing you to other agencies, you're ready with an answer, instead of starting over from scratch.

Why Founders Use PrometAI to Build

Example Structure of an Insurance Agency Business Plan

This walkthrough follows HarborShield Insurance, the sample business built into this template. Each part below explains why that section matters for an insurance agency, and shows what the sample plan actually includes.

Sections

1. Executive Overview (Mission, Vision & Business Concept)

2. Company Overview & Product Offering

3. Market Opportunity & Target Customers

4. Growth Strategy & Development Phases

5. Competitive Positioning & Strategic Analysis

6. Operations & Organizational Structure

7. Financial Overview (Revenue Model, Investment & Key Metrics)

8. Risk Management & Compliance Considerations

9. Scenario Analysis, Stress Testing & Financial Simulations

Read More

FAQs