Start with the spread on one placement. Write down the bill rate, the pay rate, the employer's payroll taxes, the workers' compensation premium for that job class and any benefits. What remains is the gross profit per hour. Multiply it by the hours a typical temp works in a week and the number of temps on assignment, and the weekly gross profit of the agency follows. Everything else in the plan, from recruiter headcount to the size of the credit line, depends on that calculation being right. Run it separately for each job class, because a forklift operator and a receptionist carry very different insurance costs.
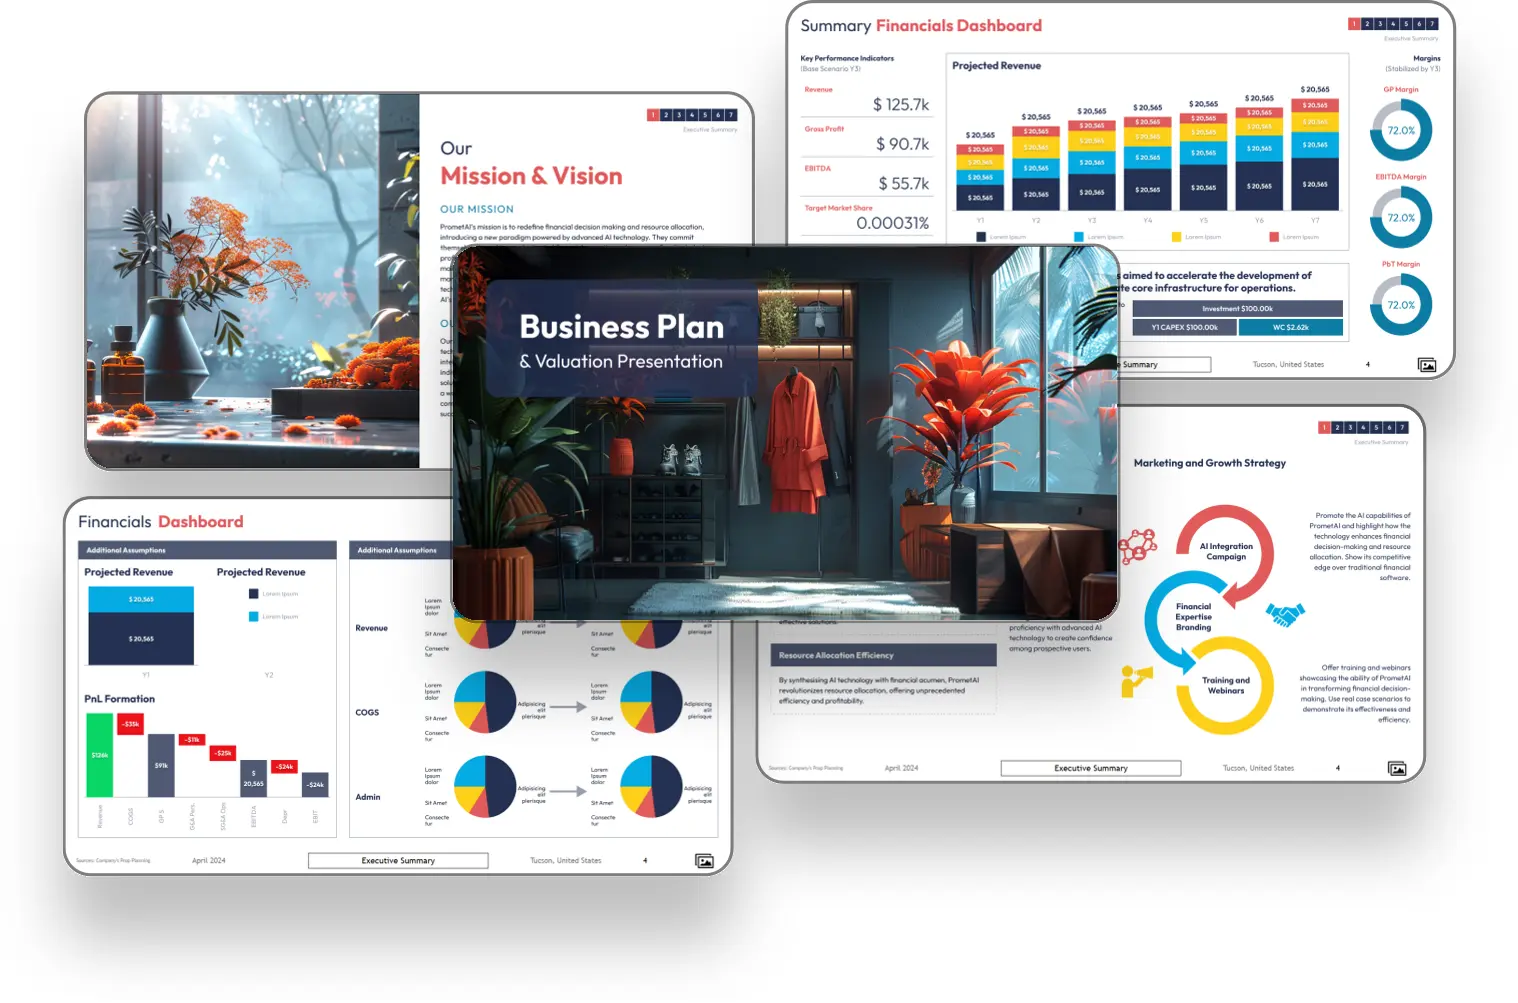
Then separate the three kinds of income. Hartwell's model divides revenue into temporary staffing at 60 percent, temp-to-hire conversion fees at 20, direct-hire fees at 10 and other income at 10; in Year 3 those lines come to $309k, $103k, $52k and $52k. Temporary staffing is steady and low-margin. Conversion and direct-hire fees are high-margin and irregular, and every conversion removes a temp from the weekly billing. A plan should forecast each on its own basis and show how the mix affects cash. It should also state the conversion fee schedule, since clients will ask how the fee reduces the longer a temp has been on assignment.
Third, describe both markets the agency serves. A staffing business has to recruit workers as well as win clients, and a shortage on either side stops growth. Set out where candidates come from, what screening and safety training they receive, and how quickly an order can be filled. Then describe the client side: which employers, which job types, what fill rate they expect. Hartwell concentrates on warehouse, light industrial and office roles, which keeps recruiting and insurance classes manageable. Its roadmap adds two further regional markets and an applicant tracking system, both of which should be costed before they are promised. That focus is a deliberate business choice and should be defended as one. An agency that tries to fill every type of role usually fills none of them quickly.
Fourth, deal with compliance directly. The agency is the legal employer of its temps. It withholds and pays payroll taxes, carries workers' compensation, and shares responsibility for workplace safety with the client. Misclassified job codes or an injury on an under-insured site can remove a year's profit. List these obligations among the financial risks, cost the insurance by job class when estimating startup costs, and explain how the agency checks a client's site before sending workers. Lenders and insurers will both ask to see the safety programme.